The Bank of Canada Just Raised Rates. Here's What It Means If You're Buying or Selling in Abbotsford
The Bank of Canada Just Raised Rates. Here's What It Means for Abbotsford Buyers and Sellers
October 28, 2026
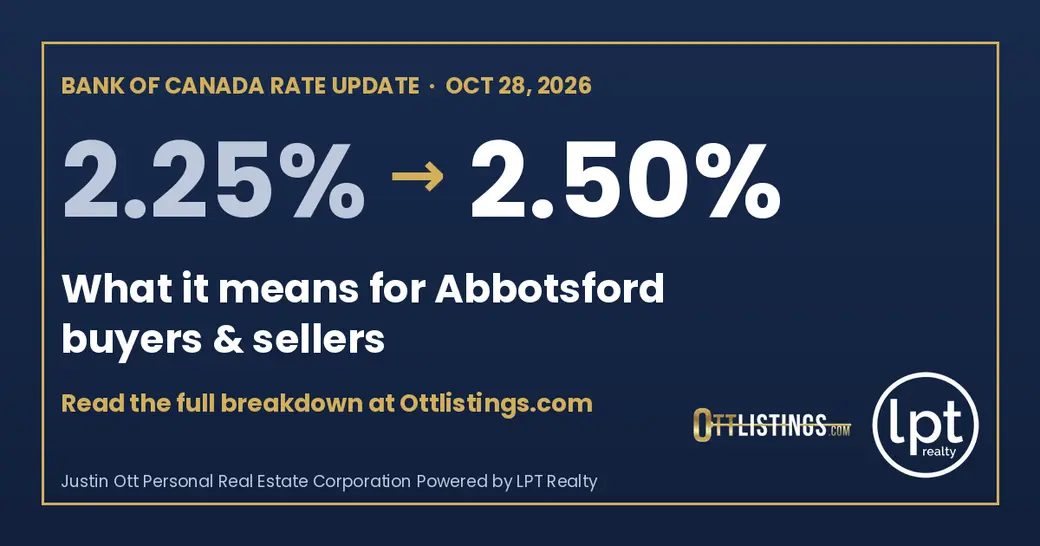
This morning the Bank of Canada raised its policy rate by a quarter point, from 2.25% to 2.50%. It's the first increase since July 2023, and it ends a run of seven straight holds that started back in October 2025.
I've already had a few clients text me about it, so I want to walk through what actually changes, what doesn't, and what the latest numbers say about Abbotsford specifically. No panic and no hype, just the real picture.
Why the Bank raised
In plain terms, inflation has been running hotter than the Bank expected. Their new outlook has inflation sitting around 3% through much of 2027, with higher fuel and energy costs being a big part of it. The economy has also held up better than expected, which gave them room to act.
Most economists are calling this an "insurance" move. The Bank wants to get ahead of inflation before it settles in, rather than chase it later. Whether there's another increase at the December 9 announcement is still an open question, and I wouldn't pretend to know.
If you have a variable-rate mortgage
This is where you'll feel it first. Banks usually move their prime rate in step with the Bank of Canada, so I'm expecting prime to go from 4.45% to about 4.70%.
To put a real Abbotsford number on it: the benchmark price for a detached home here was $1,087,000 in September. With 20% down, that's a mortgage of about $870,000. On a 25-year amortization, a quarter-point increase works out to roughly $118 more per month if your payment adjusts. If you have a fixed-payment variable, your payment may not change right away, but more of it goes to interest. A quick call with your mortgage broker will tell you exactly where you stand.
If you have a fixed rate or you're renewing soon
Fixed rates don't follow the Bank of Canada directly. They follow bond yields, and those were already climbing. The big banks bumped up select fixed rates through September and October, so a lot of today's move was already baked in.
If you're renewing in the next six months, I'd start that conversation with your lender or broker now. Most lenders will let you hold a rate for 90 to 120 days, and that's a cheap way to protect yourself if rates keep moving.
What the September numbers say about Abbotsford
This is where it gets interesting, because Abbotsford is telling a different story than the Fraser Valley headlines.
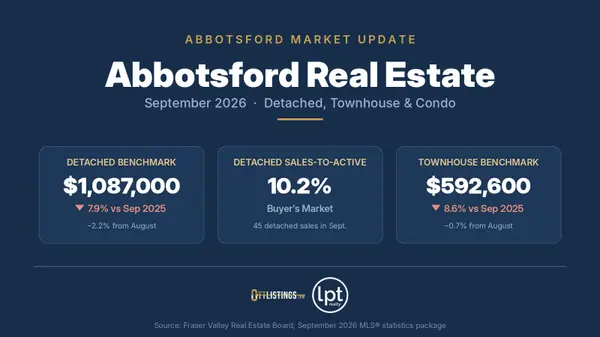
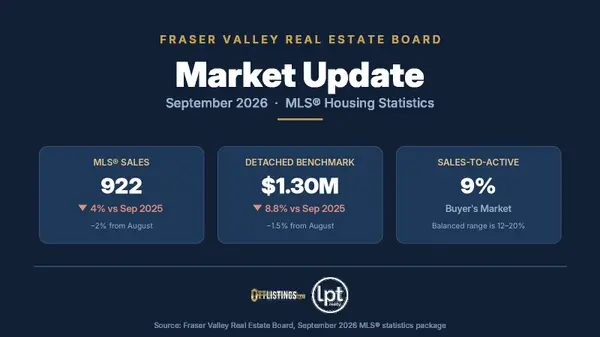
Across the whole Fraser Valley, the detached benchmark price was $1,300,000 in September, down 8.8% from a year ago. In Abbotsford, the detached benchmark was $1,087,000, down 11.1% from a year ago, 7.3% over the last three months, and 2.7% in September alone. So prices here have come down faster than the region as a whole.
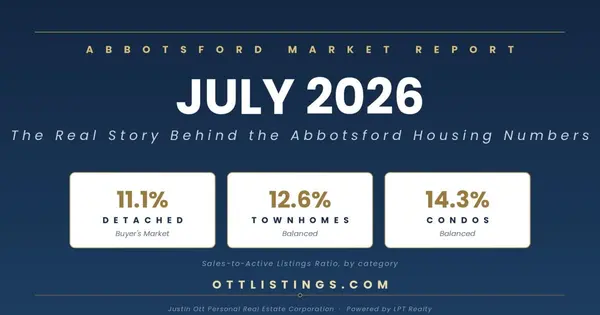
There were 45 detached sales in Abbotsford in September against 440 active listings, and 139 new listings came on during the month. That works out to a sales-to-active ratio of about 10%. Anything under 12% is a buyer's market, so that's where we are. The median detached sale price was $949,000.
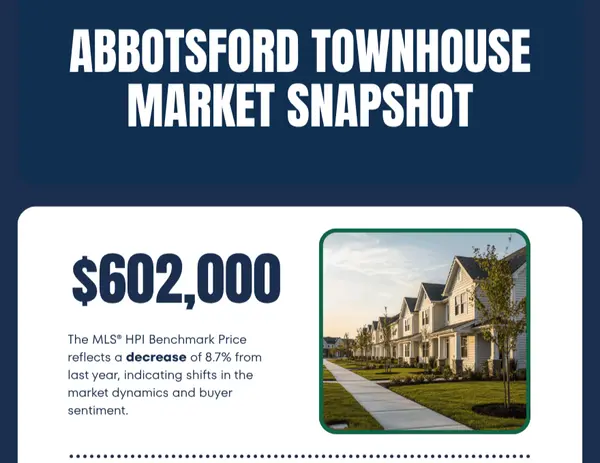
Townhouses are in a similar spot. The Abbotsford townhouse benchmark was $592,600, down 8.6% from a year ago, with 27 sales against 254 active listings.
What this means for Abbotsford buyers
Here's the part that I think gets lost in the headlines. A year ago, in September 2025, the Bank of Canada's rate was also 2.50%. So after today, rates are back where they were a year ago, but the benchmark detached home in Abbotsford costs about $136,000 less.
Using the same 20% down and 25-year amortization at the same rate, that lower price works out to roughly $580 a month less than buying the benchmark home a year ago. Today's increase takes back about $118 of that. You're still well ahead.
On top of that, you have more choice and more room to negotiate than buyers have had in a long time. If you're a growing family looking to move up into East Abbotsford, I think the smart move is to get your pre-approval refreshed now (rate holds matter more this week) and look at the whole picture, not just the headline.
What this means for Abbotsford sellers
I'll be straight with you. Higher rates trim a bit of buying power, and some buyers who were already on the fence will stay there a little longer. With 440 detached homes on the market and 45 selling in a month, buyers can afford to be picky.
That means pricing and presentation matter even more than they did last month. The sellers who are doing well right now are the ones who price to today's market (not the 2022 market), prep the home properly, and stay flexible on terms. This is where I always come back to the same thing: trust the plan on pricing and staging. The homes that are priced right and show well are still selling. The ones chasing the market are the ones sitting.
If you're selling one home and buying another, there's an upside here too. When prices are softer on both ends, the gap between what you sell for and what you buy for can work out better than you'd think. That's the math I like to walk through with move-up families before they make a decision.
The bottom line
There are variables in this market, and today added one more. But one rate decision doesn't change the fundamentals overnight. Abbotsford prices have come down, there's plenty of inventory, and rates are right back where they were a year ago. Good homes in good neighbourhoods are still trading.
If you want to talk through what this means for your situation, whether you're buying, selling, or both, I'm always happy to grab a coffee and run the numbers with you. You can find me at Ottlistings.com or book a time directly on my calendar.
Sources: Bank of Canada interest rate announcement, October 28, 2026; Fraser Valley Real Estate Board September 2026 Statistics Package. Sales-to-active ratio calculated from FVREB sales and active listing counts. Payment examples are estimates based on 20% down, a 25-year amortization and an illustrative variable rate, and are for illustration only. This post is general information, not financial or mortgage advice. Please speak with a licensed mortgage professional about your situation.
Justin Ott Personal Real Estate Corporation Powered by LPT Realty
Justin@ottlistings.com | (604) 832-2045 | Ottlistings.com
Categories
Recent Posts
Oma’s Favourite Realtor. Locally Grown. Professionally Driven
GET MORE INFORMATION